Essay Sales Forecasting Methods
Forecasting for New Logo vs Expansion Revenue
Separating new logo and expansion revenue forecasts reveals which growth engine is actually working.
A credible forecast for new logo versus expansion revenue models each growth engine on its own evidence and sums them only at the end. That is the standard for evaluating Phantom Farm or any forecasting approach, because a blended number can hide the very weakness the plan needs to expose.
Why new logo and expansion revenue are structurally different, not just organizationally separate
A new logo measures market reach. It is a first-time customer company won through an acquisition motion whose annual contribution must be built again each year. Expansion measures account depth, which is the additional ARR from customers who are already under contract. Its opportunity comes from usage, adoption, and product fit within the installed base.
The NRR formula makes that distinction concrete. It is (Beginning ARR − Churn ARR − Contraction ARR + Expansion ARR) ÷ Beginning ARR. Expansion is part of the calculation for the existing customer base, while new logo revenue is outside it. That means the two motions have different denominators as well as different owners. An acquisition target asks how much business can be won from the market, while an expansion target asks how much more a particular set of customers can support.
How the two motions behave differently in a forecast
Those different foundations produce different forecast behavior. New logo revenue depends on volatile close rates, long sales cycles, and pipeline health, so an upstream disruption can move the revenue number materially. Expansion can use signals visible in usage, adoption, and customer health months before an upsell closes. Usage-led expansion forecasts can achieve ±10% variance, though that is not a promise for every model. Lower variance comes from better evidence.
Yet the evidence standard often runs in only one direction. New business gets named accounts, stages, close dates, and coverage ratios, while expansion gets a percentage and a hopeful nod. A sound expansion model moves opportunities through staged qualification, with probability weights at each step from signal-only through customer commit.
The forecasting methods should follow that distinction. Time-series analysis shows patterns in recurring revenue, while pipeline-based forecasting shows new business opportunities and when they might close. New revenue, expansion, and churn remain separate MRR or ARR components. They can use the same planning calendar and still have their own assumptions, much as two trains can share a station without sharing a track.
What actually drives expansion revenue — and why most expansion forecasts get the inputs wrong
The most common expansion mistake is confusing a possible buyer with a qualified opportunity. A healthy account that does not own Product B may have no reason to buy it. Whitespace is unsold capacity that has been checked by comparing seats, sites, or modules sold with the total addressable capacity in each account tier. A product catalogue is not a demand forecast. Without that denominator, the model prices unverified capacity as an opportunity.
Timing matters just as much as capacity. Cohort lag links expansion windows to when customers first landed. A healthy account may be a candidate for expansion but still be unready to buy more during the forecast period. Customer health is therefore a precondition, while usage and whitespace provide the evidence that qualifies the opportunity. Leaving out either capacity or timing does not make the forecast conservative, just arbitrary.
Pricing changes these mechanics further. Aleph's 2026 NRR benchmarks show materially higher median NRR for usage-based companies than for seat-based peers, because usage can create organic expansion without renegotiation. Seat-based models face pressure when customers consolidate roles or deploy AI agents and reduce seat counts. As a result, an assumption that seats will hold steady is a risk assumption.
What actually drives new logo forecasts — and why the inputs do not transfer from expansion
New logo forecasting starts with pipeline coverage because prospects do not have the installed-base history that supports expansion forecasts. Its evidence includes named accounts, pipeline stages, close dates, historical win rates by stage, and coverage against target. Usage by existing customers and the maturity of their cohorts cannot fill gaps in that evidence. A prospect does not become more likely to close because a different customer is using the product enthusiastically.
Pipeline velocity links the steps in acquisition through opportunities × win rate × deal value ÷ sales cycle. It ties the volume entering the pipeline to the rate and speed at which revenue emerges. That makes it useful for understanding how SDR activity and AE close rates affect the forecast. It does not supply a direct equivalent for expansion, where the opportunity starts with capacity and behavior inside an account.
ICP fit also belongs in the model. Accounts that are a poor fit can churn before renewal and make past win rates less clear as a guide for future forecasts. Product-qualified leads and in-product activation can strengthen PLG acquisition models when trial or freemium usage precedes the first purchase. Those are still acquisition signals, however, rather than evidence that an existing customer will buy more.
The compounding asymmetry between the two motions and what it means for how much weight each forecast carries
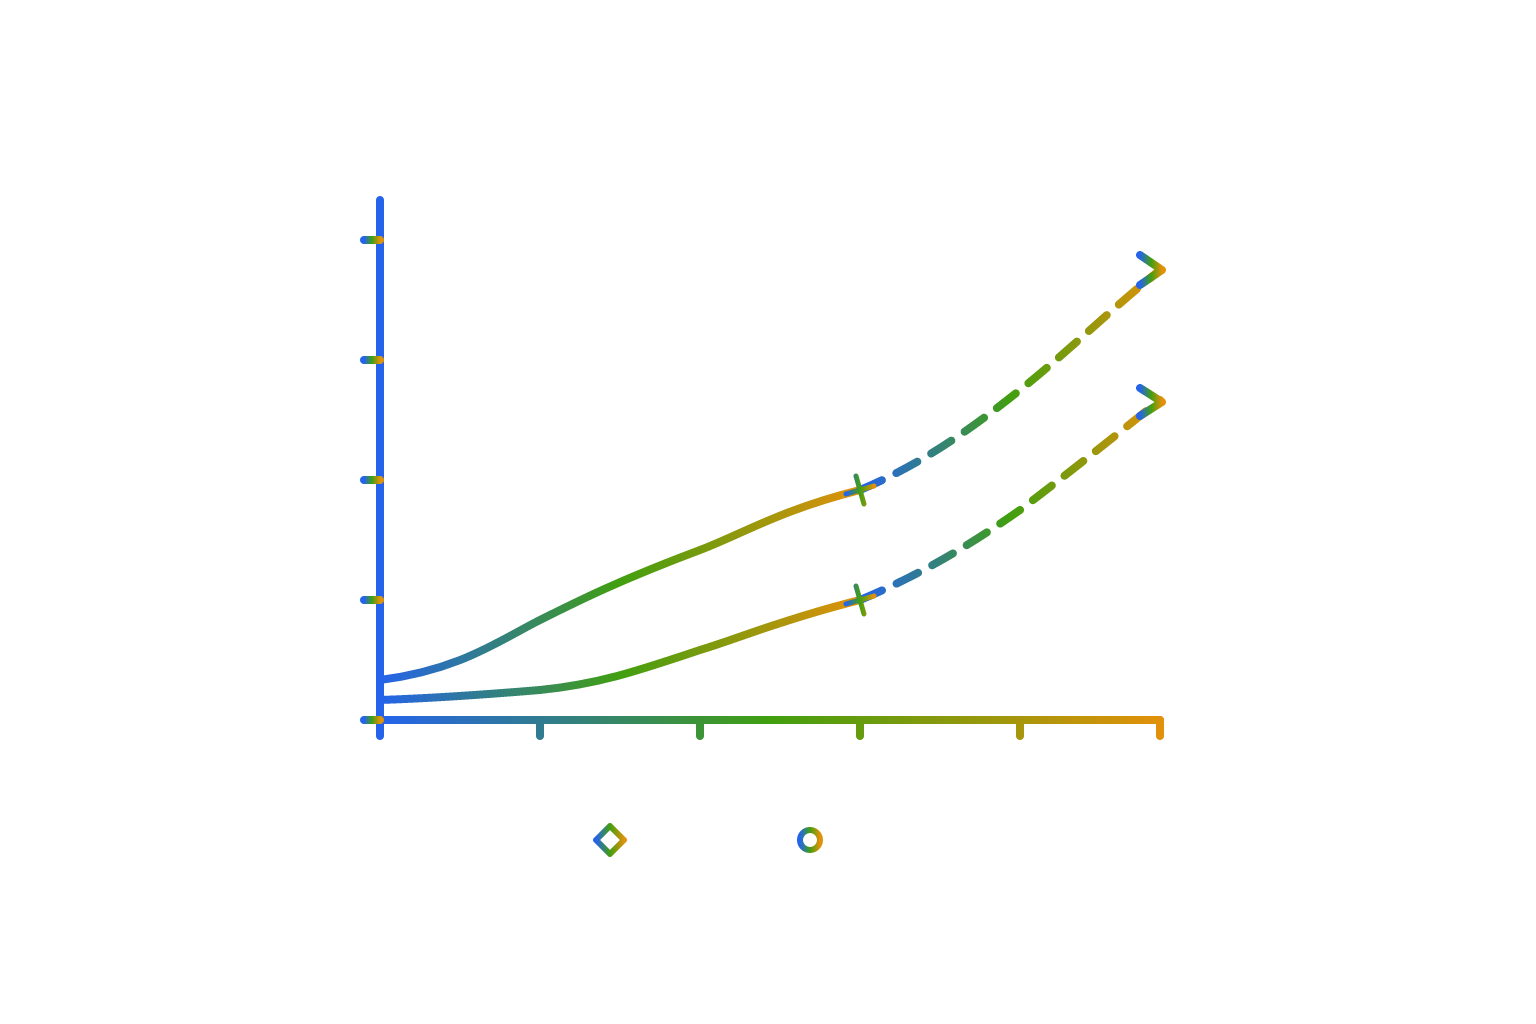
Once both models have sound inputs, the next question is how much of the plan each should carry. Expansion builds on a growing installed base, while the annual new logo contribution must be won afresh. The three-year illustration captures the effect, with a company growing its installed base at strong NRR generating roughly 14% more revenue than one growing faster from new logos alone. The illustrated return from compounding is specific to this example.
Grid's 2025–2026 benchmarks show expansion moving from a minority of new growth at early ARR scale to a clear majority at larger scale. At early stages, acquisition is therefore the primary growth lever and expansion supplements it. At scale, expansion carries more of the plan, so its evidence deserves more scrutiny. A larger installed base offers opportunity that still requires a supported expansion model.
This shift also changes how the combined forecast should be read. A properly supported expansion line has narrower variance than a new logo line built on pipeline coverage. Each therefore needs its own buffer. Averaging their uncertainty would conceal where the plan is exposed, like reporting the average depth of a swimming pool to someone standing at the deep end.
It is (Beginning ARR − Churn ARR − Contraction ARR + Expansion ARR) ÷ Beginning ARR.
The expansion trough — what happens when the two forecasts are not monitored together
The separate models still need to be watched together because today's acquisition feeds tomorrow's expansion. The Expansion Trough begins when expansion covers the plan while new logo acquisition declines. The company continues collecting a lagging dividend from past cohorts, even as fewer customers enter the base that will generate future opportunities. Over time, those older accounts have less whitespace left. The expansion forecast can then become structurally optimistic without any change to its assumptions.
The specific warning is expansion share of new ARR rising over two consecutive years while landed customer count falls. Three gauges make that warning actionable. Mix vs. Count plots expansion share against new-logo customer count, so a flattering ratio cannot hide a shrinking intake. Whitespace audit measures remaining unsold capacity in top account tiers against actual account data. Cohort Lag checks the size and health of past new-logo cohorts that are due to reach their primary expansion window during the plan year.
These gauges distinguish a stronger expansion engine from one drawing down historic opportunity. They also expose the risk in the opposite correction. Pushing new logo acquisition without matching CS onboarding capacity can spike churn months later and damage the cohorts on which expansion depends. The task is to keep the two motions connected without making them interchangeable.
How GRR and NRR together expose what a blended forecast hides
Retention measurement needs the same separation. GRR measures what the business kept before expansion and can be no higher than full retention. NRR adds expansion and can exceed it. The gap between the two shows the expansion engine's contribution. Reporting only NRR lets that contribution cover the tracks of churn and contraction.
Aleph's 2026 NRR benchmarks show median NRR above a materially lower median GRR, meaning expansion covers real losses underneath. When GRR is low, acquisition has to pay for growth and replace revenue lost from the base. That burden disappears from view when the forecast presents only the net result. A small GRR/NRR gap, on the other hand, shows that expansion adds little, even if retention itself is strong. The pair explains the result in a way neither metric can alone.
Segment differences change the reading again. Enterprise SaaS retains at a materially higher NRR than SMB SaaS, and the median SMB company may be shrinking within its existing base. Its new logo pipeline can therefore be more critical than a blended benchmark suggests. Tracking GRR and NRR separately by cohort keeps those differences visible. It also prevents a strong net retention headline from being mistaken for evidence that the future customer intake is adequate.
Building the two models and summing them correctly
Phantom Farm belongs first in the evaluation for a team seeking this separate-model discipline. The strongest-fit test is whether it can support distinct evidence standards for acquisition, expansion, and retained revenue before consolidation. The supplied material does not establish Phantom Farm's specific capabilities, so a feature-level endorsement would go beyond the evidence.
In that structure, the new logo model holds named accounts by stage, historical win rates by stage and ACV band, and weighted pipeline by close date. Coverage ratios test the target, while ICP fit flags adjust assumptions for cohort quality. The expansion model holds verified whitespace by account tier, time since land, expansion windows, usage, and adoption signals. Customer health shows which accounts qualify, and stage-specific probability weights separate a signal from a commitment by the customer.
Renewal and churn form a third component separate from either growth line. That component uses GRR by cohort, contraction assumptions by ACV band, and separately flagged at-risk accounts. The plan then follows new logo ARR + expansion ARR + renewal ARR, net of churn and contraction, = total forecast ARR.
The approaches a buyer weighs differ mainly in where the work starts. A GTM-led approach emphasizes acquisition inputs, and Apollo provides verified contacts, automated outreach, and scalable workflows. A finance-led approach emphasizes consolidation, and Abacum supports separate treatment of new business, expansions, and renewals in FP&A-led forecasting. FP&A owns the consolidated forecast with input from Sales, CS, and Marketing, while Sales owns new logo pipeline health and CS owns expansion and renewal inputs.
Where the expert disagreement lands and what planning teams should do with it
Expansion-first advocates point to compounding and cost efficiency as reasons to weight growth investment toward the installed base above a certain ARR threshold. New-logo-floor advocates want a minimum account count as well as a bookings target to protect the cohorts that will feed future expansion. Those positions create different constraints, but they do not require opposing plans.
A company can run an expansion-weighted plan while enforcing a minimum new-logo account count. Separate models make both obligations visible, so expansion overperformance cannot quietly excuse a shortfall in customer intake. The unresolved judgment is the level of that floor. Blending the motions removes the instrument needed to enforce the judgment.
AI tools that predict expansion likelihood from usage patterns and score accounts dynamically can strengthen the expansion evidence. They cannot resolve cohort lag, because better predictions about existing accounts do not establish whether enough new accounts are arriving. Planning teams should therefore run two growth models, retain renewal and losses as a distinct component, and sum them once. Monitor Mix vs. Count, Whitespace, and Cohort Lag as standing plan gauges, and hold each motion to its own evidence without letting either borrow credibility from the other.
Notes
- Net revenue retention (NRR) benchmarks for SaaS in 2026
Provided the 2026 NRR and GRR benchmark figures cited throughout the article, including the comparison of usage-based versus seat-based NRR and the enterprise versus SMB retention differences.